JPay

Screenshots
Details
- Rating
- 36.05K reviews
- Version
- 26.4.0
- Developer
- Jpay Mobile
Analysis by Norviv
I found JPay most useful when I treated it as a focused communication and money-transfer tool rather than as a complete personal-finance app. Its purpose is closely tied to staying in contact with someone in a correctional facility, and that narrow purpose matters: the app can be genuinely important for families who need one place to handle messages, photos, and financial support, but it is not designed to replace a bank, a budgeting app, or a general messaging service.
After spending time with it, my view is fairly clear. JPay is valuable because it brings several facility-related tasks into one mobile experience, yet the convenience comes with the kind of friction that is easy to underestimate until you actually need to complete a time-sensitive action. I would recommend it to people who already need JPay’s particular services, but I would not suggest downloading it casually without first understanding what role it will play in their routine.
What the app is really good at
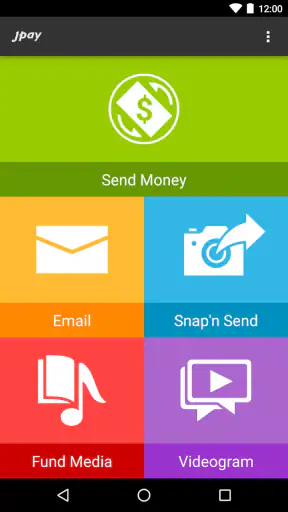
JPay is a free finance app from Jpay Mobile, although “finance” only tells part of the story. The app also supports sending and receiving emails, sharing photos, and handling other connected services. In practice, I see it as a bridge between everyday family communication and financial support. That combination is its main reason to exist, and it is also what separates it from ordinary banking or chat apps.
The most useful aspect is the way communication and money-related tasks sit close together. If you are supporting a relative or friend in custody, you may not want to switch between a normal email application, a photo-sharing service, and a separate payment workflow. JPay gives those activities a common starting point. That does not make every step effortless, but it reduces the need to remember several unrelated tools.
I also appreciate that the app is built around a specific relationship rather than around public social activity. There is no need to maintain a broad social profile or learn a complicated feed. The experience feels more task-oriented: identify the person or service you need, complete the relevant action, and return when another message or payment is necessary. For users dealing with an emotionally important but administratively demanding situation, that focus can be reassuring.
Communication is more than a side feature
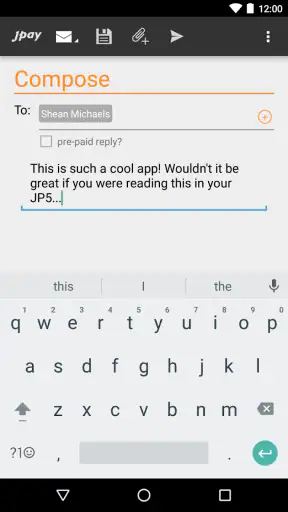
The email function is one of the reasons I would not describe JPay as merely a payment app. Staying in contact can involve short updates, practical information, encouragement, and photos that make a distant relationship feel more present. Having those elements in the same app means the user can think about support in a broader way than simply sending funds.
A realistic example would be a family member who checks in after work. They might first read a message, respond with an update about home, attach a photo from an important family moment, and then review whether financial support needs attention. That sequence is more natural in JPay than it would be if each part required a different service. The app is especially relevant when communication and financial help are connected parts of the same responsibility.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
There is also a practical emotional benefit to keeping those actions together. A person may open the app intending only to send a message and remember another task while already signed in. That can prevent missed follow-ups. I would still keep personal records outside the app, but the single-workspace approach is useful for recurring responsibilities.
Where the finance category can mislead
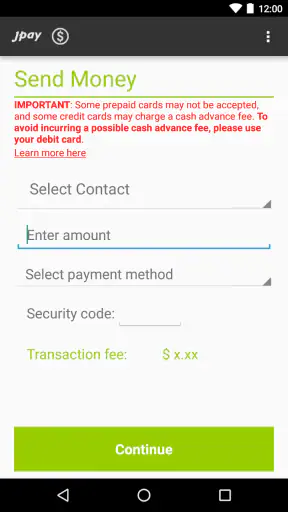
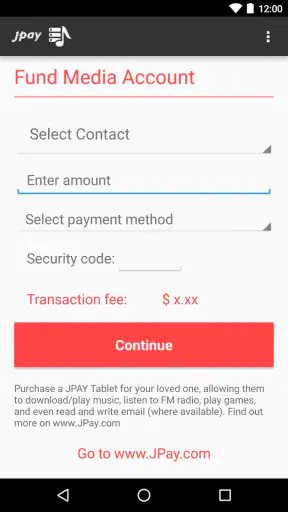
Someone searching for a finance app might expect spending charts, account aggregation, bill reminders, investment tools, or a detailed budget. JPay is not that kind of product. Its financial role is transactional and purpose-specific. It helps with sending money connected to its service environment, while its communication tools address contact with recipients. If your goal is to understand household spending or manage several bank accounts, a conventional banking or budgeting app will be a better fit.
This distinction is important before installation. JPay’s value is not measured by how many financial dashboards it includes. It is measured by whether it helps you complete the particular support and communication tasks you need. I think users who approach it with that expectation are more likely to find it useful, while users expecting a full money-management suite may be disappointed immediately.
Daily use, practical workflow, and small details that matter
My preferred way to use JPay is to separate urgent actions from routine checking. If I need to send something important, I would open the app with the recipient and purpose already in mind, complete that task, and then review the communication area afterward. This simple habit reduces the chance of confusing a message with a financial action or assuming that one completed task automatically handles another.
I would also prepare messages before opening the app when the subject is sensitive or detailed. Writing a thoughtful update in a notes app first gives me time to check names, dates, and wording without the pressure of a live transaction screen. Then I can paste or retype the final version as appropriate. This is a small workflow improvement, but it is particularly helpful when communication matters emotionally and the app is being used on a phone.
Photos deserve similar care. I would choose images deliberately rather than treating the photo option like an ordinary social-media upload. A family photo can be meaningful, but it may also contain private details in the background. Checking the image before sending is a sensible step, especially when several people or documents appear in the frame. JPay makes sharing possible, but the responsibility for choosing suitable content remains with the sender.
Another useful habit is keeping confirmation information outside the app. I would record the date, recipient, purpose, and any reference details associated with an important action. That does not mean the app is unreliable; it means financial and communication tasks are easier to track when the user maintains a simple personal log. This becomes valuable if several family members contribute support or if you need to explain what was sent and when.
The app’s narrow purpose also creates a particular trade-off. It may be faster than coordinating separate services, but it can feel less flexible than tools designed for general communication or everyday payments. A regular messaging app usually offers a more familiar conversation experience, while a bank app may provide clearer financial history. JPay’s advantage appears when the recipient and service context make those general alternatives unsuitable.
What I would check before relying on it
Before making JPay part of a weekly routine, I would confirm that the intended recipient and the required service are available through the app’s setup process. This is not a step I would skip just because the application is free. The usefulness of a specialized platform depends on matching the correct person and service, and a mistake at that stage can create unnecessary delay or confusion.
I would also avoid assuming that sending a message, sharing a photo, and sending money are identical workflows. They serve different purposes and should be reviewed separately before final confirmation. When I use an app that combines communication with financial actions, I prefer to pause at each final screen and verify the recipient, the selected action, and the amount or content. That extra moment is worthwhile.
For families sharing responsibility, agreeing on a routine can make the app easier to manage. One person might handle messages while another tracks financial support, or everyone might use a shared private record. JPay can centralize access to tasks, but it does not automatically create a family coordination system. Without a simple agreement, duplicate actions or missed updates are possible.
The main weakness: convenience does not remove uncertainty
My biggest reservation is that a specialized app can feel simple at first and still require careful attention. The presence of several related services in one place is helpful, but it also means the user must understand which part of the app they are using at any given moment. Someone in a hurry may move through the interface too quickly, especially when a message and a financial task are being handled during the same visit.
This is not the kind of app I would use casually while distracted. I would avoid completing an important action on a weak connection, in a crowded place, or when I could not carefully review the final details. The app’s purpose makes mistakes more consequential than they would be in an ordinary social application. A rushed tap is not just an inconvenience when money or a personal message is involved.
I also think the experience may feel less polished to people accustomed to modern banking apps or mainstream chat platforms. Those alternatives often have familiar navigation patterns because users interact with them every day. JPay serves a more specialized situation, so its value depends less on entertainment or elegance and more on whether it handles the required tasks clearly enough. I can accept that trade-off, but I would not pretend it disappears.
Another limitation is that JPay is not a universal solution for every kind of contact. If your main need is video conversation, broad group communication, household budgeting, or ordinary peer-to-peer payments, you should look elsewhere for the primary tool. JPay may still have a role for its supported communication and financial functions, but it should not be forced into a job it was not built to do.
The app’s audience rating is Teen, which is worth keeping in mind for households deciding who should access it. That label does not replace adult judgment about financial responsibility or the privacy of messages and photos. I would treat access as something to discuss within the family, particularly if a younger person is helping with communication but should not be responsible for financial decisions.
Performance expectations and platform fit
JPay’s current version is 26.4.0, and it requires at least iOS or Android version 11. That requirement is reasonable for many current phones, but it can matter if you are trying to use an older device. Before planning around the app, I would check the operating system rather than assuming that any phone capable of installing ordinary messaging apps will support it.
The app has been available since October 15, 2012, and its long presence suggests that it is an established part of this service category rather than a new experiment. Its audience is substantial, with over five million installs, while the average rating is 3.9 from around one hundred four thousand ratings and roughly thirty-six thousand written reviews. I read that combination as a sign of practical usefulness mixed with real user frustration, not as a reason to expect a flawless experience.
Those figures are best understood in context. A specialized app can receive criticism because a payment, message, or account issue matters deeply to the people using it. At the same time, a large installed base does not guarantee that every facility, recipient, or workflow will feel identical. I would use the app for its intended purpose, but I would still verify important outcomes and keep personal records rather than relying on an icon or notification alone.
Who should use JPay, and who should choose something else?
I think JPay is a strong candidate for people who regularly need to communicate with someone in a correctional facility while also managing related financial support. It is especially suitable for a family member who wants one mobile location for messages, photos, and money-related tasks. The app’s free price lowers the barrier to trying it, although users should still pay close attention to the details of each service they use.
It can also suit someone who is not particularly comfortable juggling several digital platforms. The app does not eliminate every complication, but centralizing the relevant functions may be easier than remembering which tool handles which part of the relationship. I would recommend establishing a calm, repeatable routine rather than exploring the app only when an urgent need appears.
I would be more cautious about recommending it to someone who only wants a general way to send money. A normal banking or payment application may offer a more familiar transaction history and broader recipient options. Likewise, someone who simply wants to exchange everyday messages and photos with friends or relatives outside JPay’s service setting will probably have a better experience with a standard messaging platform.
It is also not my first choice for users seeking detailed financial control. If you need categories, budgets, recurring household planning, or a full view of your finances, JPay is too narrow. I would use a dedicated finance tool alongside it, not expect JPay to become the center of my entire financial life.
For older phones, the operating-system requirement may be decisive. A user who cannot update to version 11 or later should not build an important communication plan around the app without first finding a compatible alternative. This is one of those practical checks that takes little time and can prevent a frustrating installation attempt.
My final view after using it
JPay succeeds when its specialized purpose matches the user’s real situation. I like the way it connects financial support with email and photo communication, because those activities often belong to the same family responsibility. The app is free, established, and focused enough to be useful without pretending to be a complete bank or social network.
Still, I would approach it with care. I would verify recipients, review each action separately, keep a private record of important transactions, and avoid treating the app as a replacement for ordinary budgeting or general messaging tools. Those habits are not signs that the app has no value; they are what make a specialized service safer and more manageable in daily use.
My recommendation is straightforward: if you need JPay’s particular combination of contact and financial support, it is worth trying and may become an important part of your routine. If you are simply looking for a normal payment app, a family chat service, or a personal finance dashboard, I would choose a tool built specifically for that job instead. JPay is at its best when you need exactly what it offers, and its limits become much clearer when you do not.
Frequently Asked Questions
01What is JPay used for?
JPay is a communication and payment service designed primarily for people who want to send money, emails, photos, video greetings, and other approved services to individuals incarcerated in participating correctional facilities. Availability depends on the facility and jurisdiction, so the features shown in the app may vary. Before downloading, users should confirm that the intended correctional institution supports JPay and the specific service they need.
02Can I send money through the JPay app?
Yes, JPay generally allows users to send funds to eligible incarcerated individuals, although supported payment methods, transfer limits, fees, and delivery times can differ by state and facility. The app normally displays the applicable charges before a transaction is completed. It is important to verify the recipient’s identification details carefully, because corrections to a completed transfer may be limited and refunds are not always immediate.
03Can I send emails, photos, or video messages with JPay?
In participating facilities, JPay may let users exchange electronic messages and send approved photos or short video greetings. Every message or attachment can be subject to institutional screening, content rules, size limits, and approval delays. Some facilities may not offer all communication options, and messages are not necessarily delivered instantly. Users should review the recipient facility’s regulations before purchasing stamps or sending media.
04How much does JPay cost, and are there additional fees?
JPay is free to download, but many of its services involve separate charges. Sending money, purchasing email stamps, ordering media services, or making certain payments may include transaction fees that vary according to the facility, amount, and service selected. The final cost should be checked carefully during checkout. Because pricing and policies can change, users should rely on the current in-app information rather than older reviews or unofficial fee lists.
05Is JPay safe and available on every phone or correctional facility?
JPay uses account access and payment processing features intended to protect user information, but no online service can eliminate every security risk. Users should download the official app, use a strong unique password, and avoid sharing account or payment details. The app is not universally supported: participating facilities, available services, device compatibility, and regional restrictions determine whether JPay will work for a particular recipient.


